This is not investment advice and nothing here is a buy or sell idea.
Share buybacks are usually reported in dollars and share counts. Our Gold-Oz Screener (GAVF v2.2) asks something different: what happens if you measure a company in troy ounces of gold instead of in currency? We ran 36 large US and Nordic companies through the screener. Who actually got smaller, and did it help shareholders in gold terms?
1. Who shrank, who issued
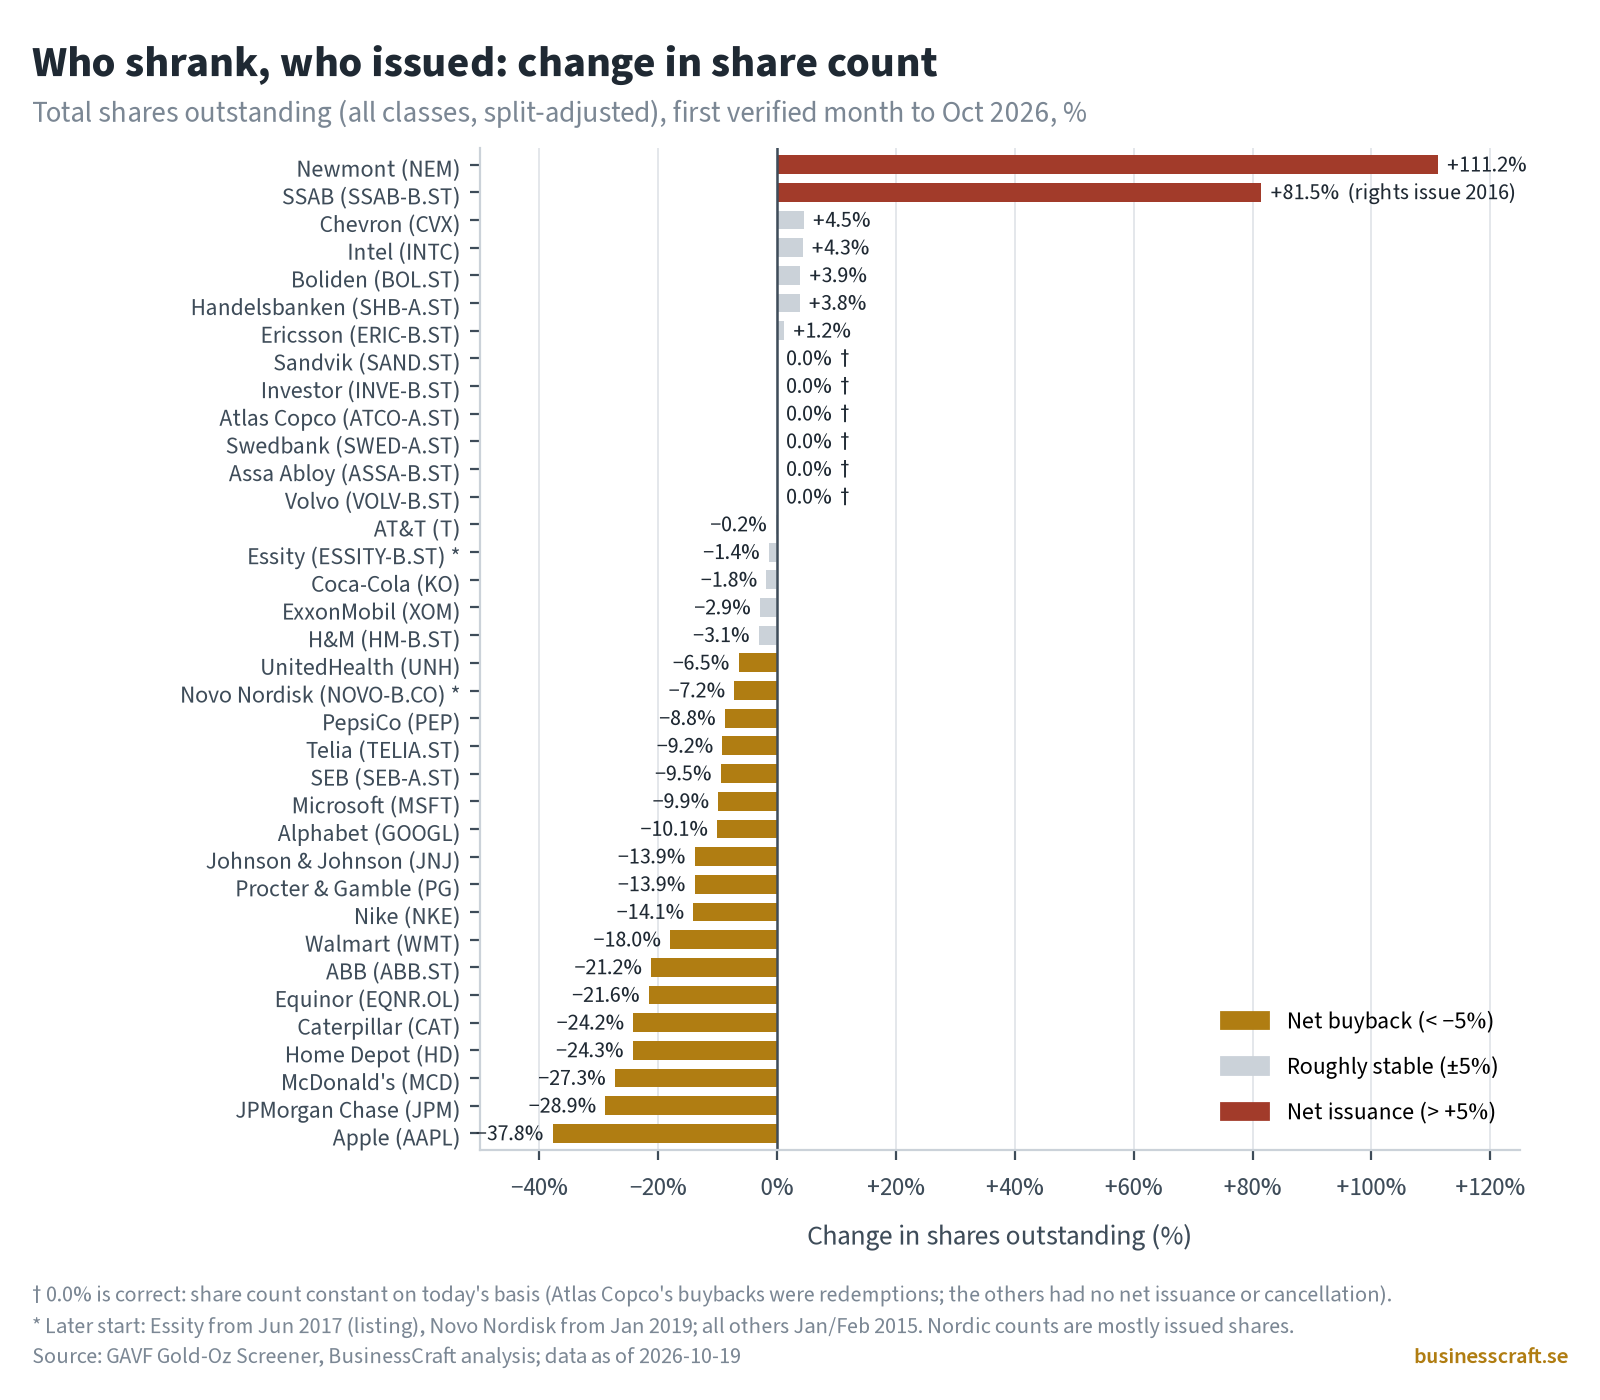
From early 2015 to October 2026, 18 of the 36 companies cut their share count by more than 5%. Apple cut its count the most, by 37.8%, followed by JPMorgan Chase (−28.9%), McDonald’s (−27.3%), Home Depot (−24.3%) and Caterpillar (−24.2%). Two companies went the other way: Newmont’s share count rose 111.2%, and SSAB’s rose 81.5%, which came from its 2016 rights issue. The other 16 stayed within ±5%. Six of them show exactly 0.0%: Sandvik, Investor, Atlas Copco, Swedbank, Assa Abloy and Volvo. That is correct: on today’s share basis their counts never changed. Atlas Copco returned cash through redemption programmes rather than by cancelling bought-back shares, and the other five had no net issuance or cancellation. Share counts are split-adjusted and include all share classes. Essity starts in June 2017, when it listed, and Novo Nordisk starts in January 2019.
2. Per share versus the whole company
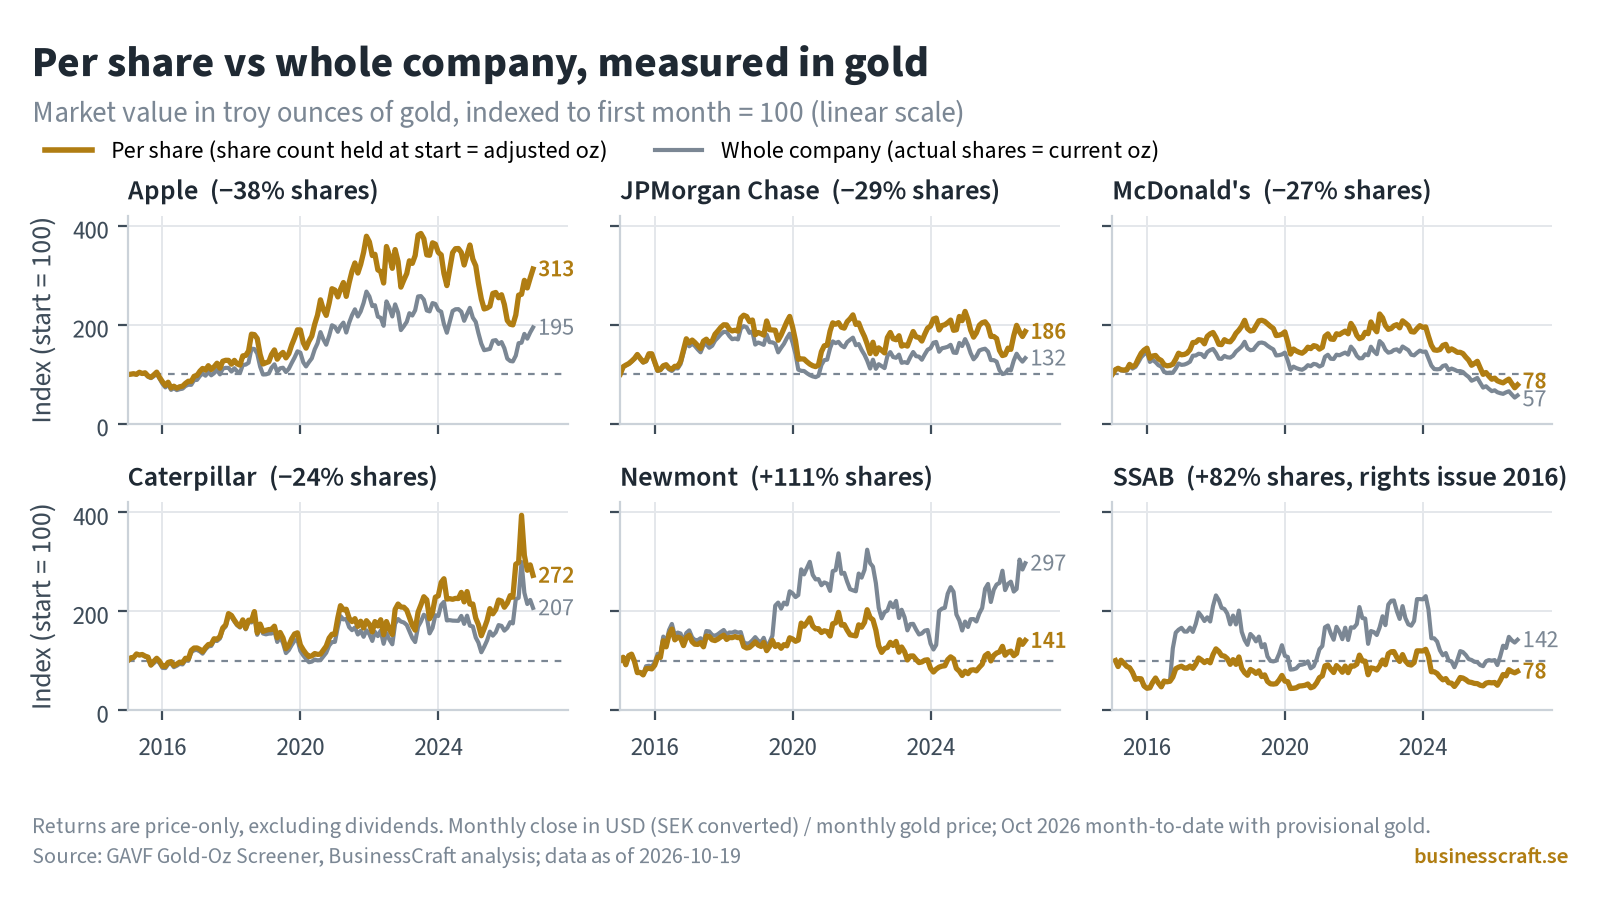
Each panel shows two lines, both indexed to 100 at the start. The gold line is the per-share value in gold: market value with the share count held at its 2015 level. The grey line is the whole company in gold, using the actual share count. Buybacks push the gold line above the grey one, and issuance pushes it below.
Apple’s per-share value in gold ended at 313, while the whole company ended at 195. JPMorgan ended at 186 versus 132, and Caterpillar at 272 versus 207. McDonald’s is the reminder that buybacks don’t guarantee anything. Its whole company shrank to 57 in gold terms and its per-share value to 78, so the buybacks softened the fall without preventing it. Newmont is the mirror image. The company grew to 297 in gold, mostly by issuing shares, but per-share value only reached 141. SSAB shows the same pattern. After its 2016 rights issue, the company ended at 142 and per-share value at 78.
All returns here are price-only, excluding dividends. Total returns are therefore understated, most of all for companies that pay out a lot.
3. How big is each company in gold?
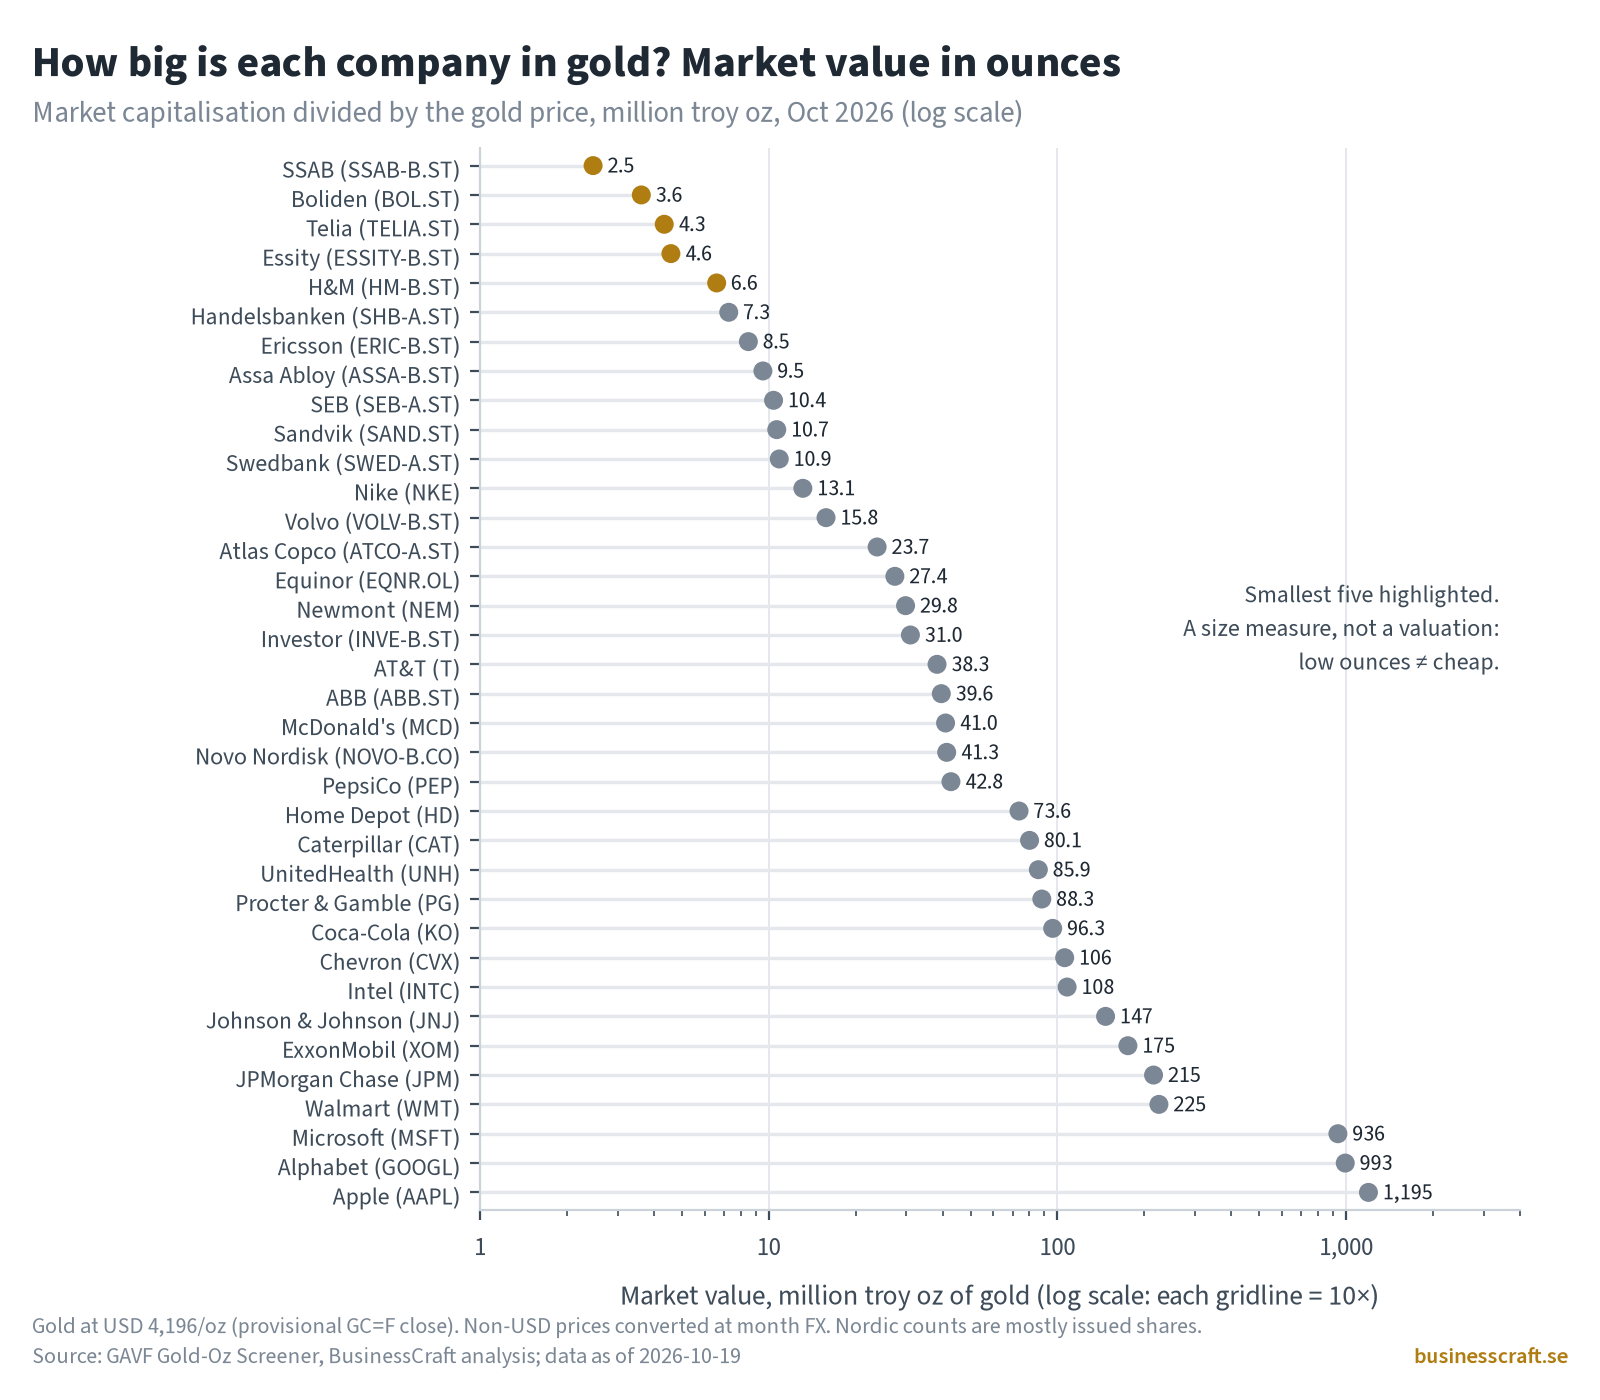
At a provisional gold price of USD 4,196/oz, Apple is worth about 1,195 million ounces, Alphabet 993 million and Microsoft 936 million. The smallest companies in our sample are SSAB (2.5 million oz), Boliden (3.6), Telia (4.3), Essity (4.6) and H&M (6.6).
This is a measure of size, not of value. A low ounce figure just means a smaller company. It doesn’t make the company cheap, and nothing in the next section suggests it predicts anything.
4. Did low ounce levels predict anything?
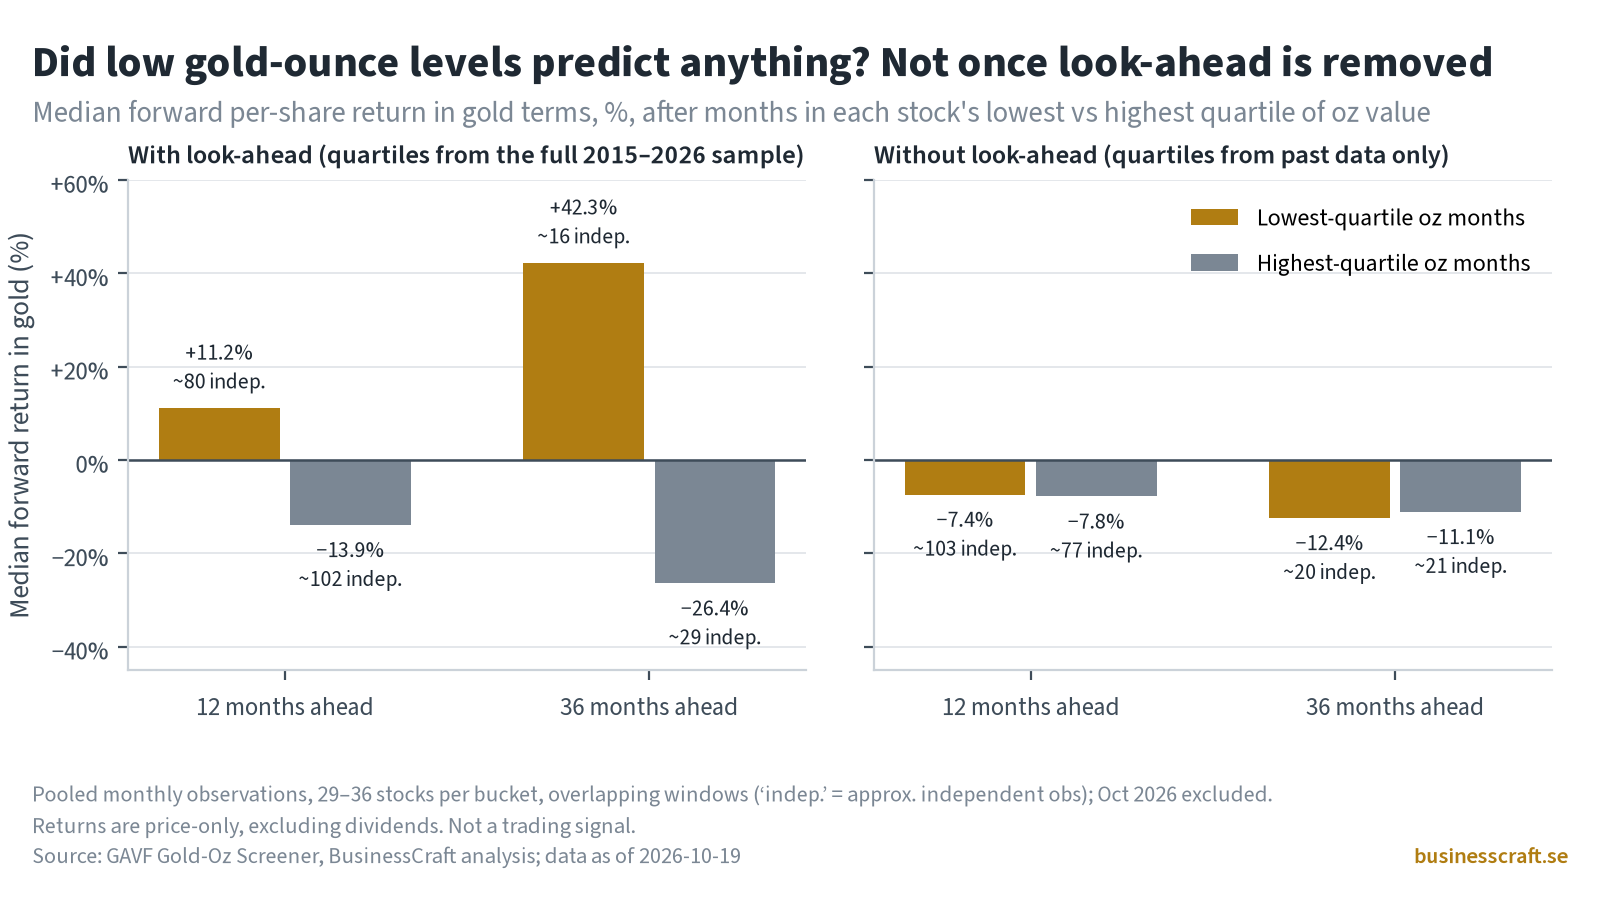
As before, returns are price-only, excluding dividends. We checked whether months when a stock sat in its own lowest quartile of gold-ounce value were followed by better per-share gold returns than months in its highest quartile.
Run naively, with quartiles taken from the full 2015–2026 history, the answer looks like a clear yes. At 36 months the median was +42.3% after low months and −26.4% after high months. But that version uses future data: whether a month counts as “low” depends on prices that came later.
Once the quartiles are built only from data available at the time, the gap disappears. At 12 months the medians were −7.4% (low) and −7.8% (high). At 36 months they were −12.4% and −11.1%. The averages lean slightly towards the low bucket (−1.8% vs −5.9% at 12 months, and −5.1% vs −6.8% at 36 months), but with overlapping windows and only about 20 independent observations per bucket at 36 months, that is well within noise. We found no edge.
Limits and caveats
- 36 companies, one period (2015–2026), heavily shaped by gold’s rise from a USD 1,251 monthly average in January 2015.
- All returns are price-only, excluding dividends.
- October 2026 is month-to-date, and its gold price is a provisional futures close. Earlier months divide a month-end share price by the LBMA monthly average gold price.
- Nordic share counts are mostly issued shares, so treasury shares (about 1–3%) are not deducted. Some yfinance price histories adjust for spin-offs (for example Atlas Copco’s Epiroc in 2018) without recording them, which can distort early ounce levels.
- No statistical significance test was run in v2.2.
Source: GAVF Gold-Oz Screener, BusinessCraft analysis; data as of 2026-10-19. Not investment advice.
Related reading: Global gold mining leaders 2025, the evolution of money from Bretton Woods to fiat and the debt reckoning.